You’ve just received your Crédit Agricole card at the agency or in the mailbox, and the first instinct is often to attempt a contactless payment. Result: refusal at the checkout. The card is there, the PIN code too, but it remains inactive until a specific action has been taken. This activation step, quick in theory, regularly blocks customers who don’t know where to start.
Inactive Crédit Agricole card: what really happens on the system side
When the bank issues a new card, it is delivered in a locked state. Contactless payment, online payment, and even ATM withdrawals are disabled until the cardholder has confirmed that they are in possession of the physical card.
The mechanism is based on a security logic: the card only activates after an operation requiring the entry of the PIN code. It is this entry that confirms to the banking network that the legitimate holder possesses the card. A contactless payment or an online purchase is not sufficient, as they do not necessarily require the confidential code.
Specifically, two operations trigger the activation: a cash withdrawal at an ATM or a payment at a merchant with PIN entry. Either one works, and the card switches to active mode in the seconds that follow. Nothing more to do.
Several regional branches of Crédit Agricole also offer the option to activate your Crédit Agricole bank card directly from the online customer area or the Ma Banque app, without going through an ATM or a merchant. Feedback on this point varies depending on the regional branch, as not all have rolled out this option at the same pace.
Activation by withdrawal or payment with PIN: the classic method
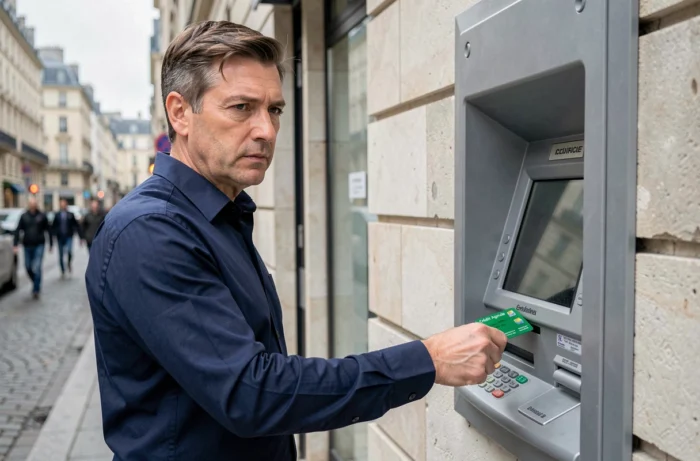
The most reliable procedure remains going through an ATM. You insert the card, enter the confidential code received separately by mail, and make a withdrawal, even for a small amount. The withdrawal at the ATM activates the card immediately.
For those who prefer not to withdraw cash, a purchase in-store with PIN entry works the same way. The merchant’s payment terminal plays exactly the same role as the ATM: it transmits the PIN validation to the network.
Points to check before going to the ATM
- The PIN code has been received by separate mail. If the card arrives before the code, you must wait: without the code, no activation is possible.
- The card is not expired before even being activated. On a late renewal, the expiration date printed on the plastic must be later than today’s date.
- The ATM used accepts the card’s network (Visa or Mastercard depending on the subscription). In France, almost all machines accept both networks, but abroad, it’s better to check.
Once the code is entered and the operation validated, all services related to the card become operational: contactless payment, online payment, and subsequent withdrawals without restriction.
Activation from the Ma Banque app and card settings management
Crédit Agricole has generalized a card management panel accessible from the Ma Banque mobile app and the web customer area. This panel allows you to manage the card’s features in real-time: activation or deactivation of remote payment, payment abroad, and adjustment of withdrawal and payment limits.
Changes take effect almost immediately, which is particularly useful for temporary limit increases before a trip or a significant purchase. You adjust, validate, and the new limit applies without delay.
SécuriPass and strong authentication for online payments
Activating the card is not always enough to pay online. Under the European DSP2 directive on strong authentication, Crédit Agricole has generalized SécuriPass as a validation device for online payments. Without this service activated, some remote transactions will be refused even if the card is functional.
SécuriPass is activated from the Ma Banque app. You associate it with your mobile device, and each online payment triggers a notification requesting biometric or code validation. If you haven’t configured SécuriPass, you will be blocked when finalizing a purchase on a merchant site, even though the card itself is perfectly active.
- Download the Ma Banque app from the store corresponding to your device (Android or iOS).
- Log in with your customer area credentials, then access the SécuriPass section in the security settings.
- Associate your smartphone by following the validation instructions (a confirmation SMS is usually sent).
- Test with a small online purchase to verify that the validation notification arrives correctly.
Replacement card after loss or theft: activation specifics
When you receive a replacement card after a report, the activation procedure remains the same: withdrawal or payment with PIN. However, the PIN code may change depending on the case. In a standard renewal at expiration, the code usually remains the same. After a report for theft, a new code is often issued.
You must therefore carefully monitor your mail in the days following the receipt of the new card. If no new code arrives, the old code is probably still valid, but in case of doubt, a call to the agency clears up the ambiguity in a few minutes.
The Ma Banque app also offers a virtual emergency card, viewable while waiting for the new physical card to arrive. This virtual card allows for online purchases but cannot be used for in-store payments or cash withdrawals.
The time between the replacement request and the actual receipt varies from one regional branch to another. Expect a few business days on average, more during the summer or peak demand periods. Having set up mobile payment on your smartphone before losing the physical card prevents you from being completely stranded during this wait.


